

Teachers Just Won at Least 28.3 Per Cent: What the New Deal Does to Borrowing Power (2026)
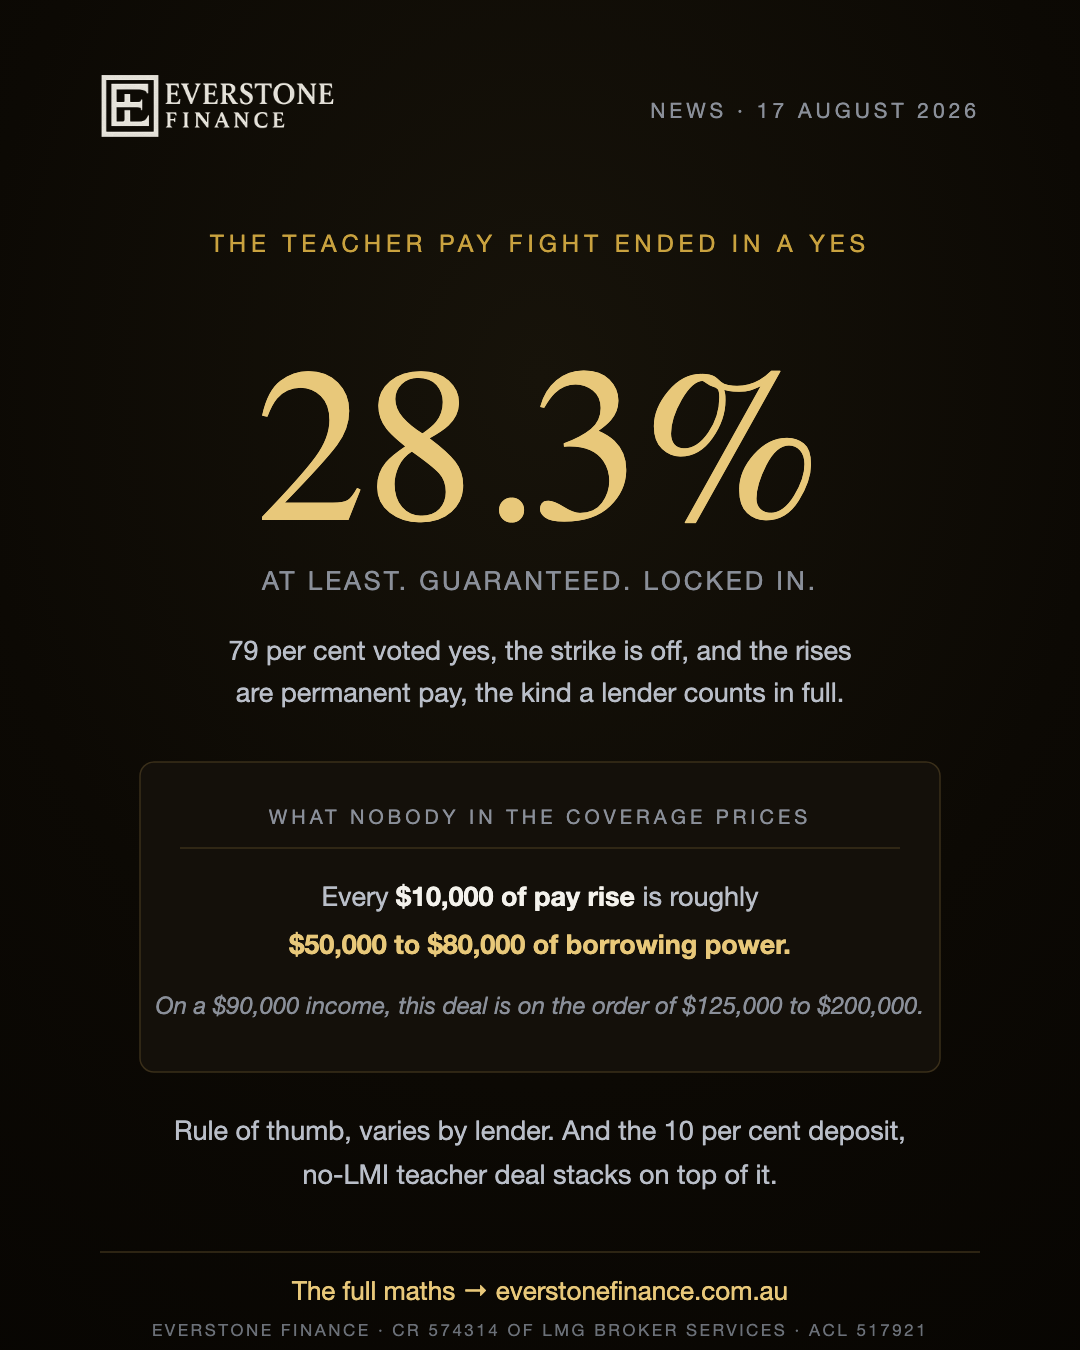
- The pay fight is over, and teachers won big. On 17 August, AEU members voted 79 per cent yes, on an 89 per cent turnout, to the government’s 10 August offer: guaranteed pay rises of at least 28.3 per cent over the new agreement, plus reduced meeting hours and improved conditions. The 19 August stopwork is off.
- Nobody covers what a rise that size means for a mortgage, so here it is: as a broker’s rule of thumb, every $10,000 of extra gross income supports roughly $50,000 to $80,000 of additional borrowing capacity on current assessment settings, varying by lender and circumstances. A rise that size compounds into real house-buying power.
- The part teachers control today: the levers that stack on top of the deal. Teacher-specific lending policy (10 per cent deposit with no LMI at select lenders), allowances counted properly, and a soft, negotiable market that is not waiting for the dispute to resolve.
- When does the rise count at a bank? Once the new rates flow through your payslips, and at some lenders earlier, on the published agreement or an employer letter. Any backdated component lands as a lump sum: deposit fuel, not assessable income.
How the pay fight ended
Victoria’s teacher pay dispute ended on 17 August 2026 when Australian Education Union members voted 79 per cent in favour of the government’s 10 August offer, on an 89 per cent turnout, locking in guaranteed pay rises of at least 28.3 per cent over the new agreement alongside reduced meeting hours and improved conditions, as reported by EducationHQ. The 24-hour statewide stopwork planned for 19 August will not go ahead, ending a campaign that produced two strikes and a year of negotiation.
The ballot closed at 10am on 17 August and the result was emphatic: 79 per cent yes, on an 89 per cent turnout. The deal locks in guaranteed rises of at least 28.3 per cent over the new agreement, with reduced meeting hours and improved conditions alongside, and the third statewide stopwork planned for 19 August is off. A year of negotiation, two strikes and a rejected 12 per cent offer ended with a headline number larger than the union’s original 25 per cent claim.
We covered the strike itself, and the lending deal that quietly improved while everyone argued, in our teachers strike piece. This article is about the number nobody in the coverage touches: what the outcome is actually worth at a bank.
What a pay rise does to borrowing power
Borrowing capacity responds strongly to income growth because assessed living expenses do not rise in step with a pay rise: most of each extra dollar lands in the serviceability surplus. As a broker’s rule of thumb on current assessment settings, every $10,000 of additional gross income supports roughly $50,000 to $80,000 of extra borrowing capacity, with the exact figure depending on the lender, existing debts, dependants and expenses. On that arithmetic the new agreement’s guaranteed rises of at least 28.3 per cent compound into a six-figure difference in what a lender will write for the same teacher.
Here is the mechanism, minus the jargon. When a lender works out what you can borrow, it stacks your income against your assessed living costs, existing commitments and a stress-tested repayment. A pay rise does something disproportionate in that equation: your expenses are already covered, so almost all of the new income lands on the side of the scales that says yes. That is why capacity grows faster than pay does.
The rule of thumb we use in practice: every $10,000 of extra gross income supports roughly $50,000 to $80,000 of additional borrowing, depending on the lender’s settings and your circumstances. Run the new deal through that lens, on a round-number illustration of a $90,000 income: rises of at least 28.3 per cent add roughly $25,500 of gross income by the end of the agreement, which on common assessment settings is on the order of $125,000 to $200,000 of borrowing capacity, before any promotion or allowance moves the number again. That is not a rounding error. In most of Melbourne that is the difference between suburbs.
Two honest caveats. First, these are rules of thumb: the precise figure is lender-specific and personal, which is exactly what a serviceability assessment is for. Second, capacity is not a target: the number a lender will write and the number you should borrow are different conversations, and we have both with clients.
See what the new pay deal is worth in borrowing power.
A former banker runs the ratified rise through real lender calculators and shows which lenders count it now, free.
Get your borrowing power checked, freeRather message than book? WhatsApp or text Ahmed after class, or call him, about what the new pay deal does for your borrowing. His own mobile, no call centre, and the first chat is free.
The levers that stack on top of the new deal
The new deal multiplies, rather than replaces, the levers teachers already had: profession-specific lending policy already offers a 10 per cent deposit with no lenders mortgage insurance at select lenders, allowances and part-time loads can be counted more generously by some lenders than others, and August 2026 market conditions favour buyers, with applications down at the biggest lenders, auction clearances below 50 per cent and negotiation back in fashion. Policy selection across lenders typically moves the outcome more than any single pay decision.
With the pay outcome locked in, three levers stack on top of it:
- The teacher deal itself. Select lenders offer teachers a 10 per cent deposit with no LMI, which on a typical Melbourne purchase is a five-figure saving and years off the savings timeline. The full policy picture, including how allowances and part-time loads are read, is in our teacher home loans guide.
- Lender selection on income treatment. Two lenders can look at the same teacher and reach materially different capacity numbers, because they count allowances, second jobs and part-time patterns differently. This spread is usually worth more than the pay rise being argued about, and finding it is precisely a broker’s job.
- The market is cooperating. Applications are down at the country’s biggest lenders, auction clearances have sat below 50 per cent since late May, and vendors are negotiating again: the full picture is in our buyer’s market piece. Waiting for the pay outcome means shopping in whatever market exists afterwards, and the current one has more give in it than most.
When lenders count a new pay rate
Lenders generally assess income on current evidence: once a new agreement’s rate appears in payslips it is counted, and many lenders will also accept a formal employer letter or the published agreement confirming a locked-in future rate, treatment varying by lender. Backdated pay lands as a lump sum and helps savings rather than assessed income, while scheduled future increments under an enterprise agreement can sometimes be counted early by lenders comfortable with documented certainty. A broker’s role in an agreement year is matching the evidence a teacher can produce to the lender that will read it most generously.
Now the deal is done, the practical wrinkle matters more than ever: lenders lend against evidence, not announcements. When a new agreement lands, the new rate counts once it shows up in your payslips, and some lenders will move earlier on an employer letter or the published agreement where the future rate is locked in. Any backdated component arrives as a lump sum: pleasant, and useful for the deposit, but it is savings, not assessable income. If your agreement includes stepped future increases, a handful of lenders will entertain the documented schedule; most want to see the money flowing first. The practical answer, as usual, is to match your paperwork to the right lender rather than the nearest one.
Frequently asked questions
Does a pay rise increase how much I can borrow?
Yes, and by more than proportionally: because assessed living expenses do not rise with your pay, most of each extra dollar of gross income lands in the serviceability surplus. As a rule of thumb, every $10,000 of additional gross income supports roughly $50,000 to $80,000 of extra borrowing capacity, varying by lender and personal circumstances.
Is the 19 August strike still going ahead?
No. AEU members voted 79 per cent in favour of the government’s 10 August offer, with the result announced on 17 August, so the planned stopwork was called off. The new agreement’s guaranteed rises of at least 28.3 per cent now move to implementation.
When would a new pay agreement start counting toward my borrowing power?
Generally once the new rate appears in your payslips, though many lenders will accept a formal employer letter or the published agreement confirming a locked-in rate, and treatment varies. Backdated pay counts as a lump sum toward savings rather than as assessable income.
What is the teacher home loan deal?
Select lenders offer teachers a 10 per cent deposit with no lenders mortgage insurance, alongside differences in how allowances, part-time loads and second jobs are counted. The details, and which teachers qualify, are covered in our dedicated teacher home loans guide.
Do teaching allowances count as income for a mortgage?
With the right lender, yes: many count regular allowances and higher-duties payments, some in full and some shaded, and the differences between lenders are material. Evidence of regularity, usually through payslips and an employment letter, is what unlocks the fuller treatment.
Should I wait until the new pay rates hit my payslip before buying?
Not necessarily: capacity can be assessed on current income now and revisited as the new rates land, and some lenders will consider a documented, locked-in future rate earlier. Market conditions also remain buyer-friendly, with applications down at major lenders and clearance rates below 50 per cent, and they will not wait for payroll systems to catch up.
Does part-time teaching reduce borrowing power?
It reduces income, which reduces capacity, but lenders differ meaningfully in how they annualise part-time and casual teaching loads and whether they count a second income stream. Policy selection matters more for part-time teachers than for almost anyone else in the profession.
What could the new 28.3 per cent deal mean for a mortgage?
On a round-number $90,000 income, rises of at least 28.3 per cent add roughly $25,500 of gross income by the end of the agreement, which on common assessment settings is on the order of $125,000 to $200,000 of borrowing capacity. The exact figure is lender-specific, and a serviceability assessment gives the real number.
The honest summary
The coverage will tally the deal in percentages and press conferences. What it will not tell you is that the outcome is denominated in borrowing power as much as in pay: at least 28.3 per cent is, for a teacher with buying plans, the difference between price brackets. The number has landed. What remains in your control are the levers that stack on top of it: the 10 per cent no-LMI teacher policy, the lender whose income treatment reads your payslips most generously, and a market that is currently negotiating. A former banker can price all three in one conversation, and the assessment costs nothing.
Want your number at today’s pay, and at the new rates? One conversation.
A former banker runs your serviceability across more than 40 lenders, shows what the teacher policy is worth on your deposit, and maps what the new agreement does to the number. Free, honest, and no obligation to act on it.
Book a chat with a former bankerAbout the author. Ahmed Lotfi is co-founder of Everstone Finance and a former banker who now works as a mortgage and finance broker in South Yarra, Melbourne, arranging home, investment and commercial lending for clients across Australia and abroad. Everstone Finance operates under the Best Interests Duty.