
The Australian Dollar Is Holding Above 70 US Cents. If Your Business Imports, Your Margin Just Widened (2026)
A business buying USD $500,000 of stock a year is paying roughly $68,000 less for it than it did last November, and most owners have not noticed, because the saving arrives one shipment at a time. That is the fastest margin improvement most importers have seen in years, and it came from nothing they did. This piece is about what to do with a margin the currency handed you and can take back: the arithmetic, the four moves that make it permanent, and why the bank reads your numbers best while the improvement is still in them.
- The Australian dollar is consolidating above 70 US cents, up roughly 8 per cent over the past year, after touching three-year highs earlier in 2026.
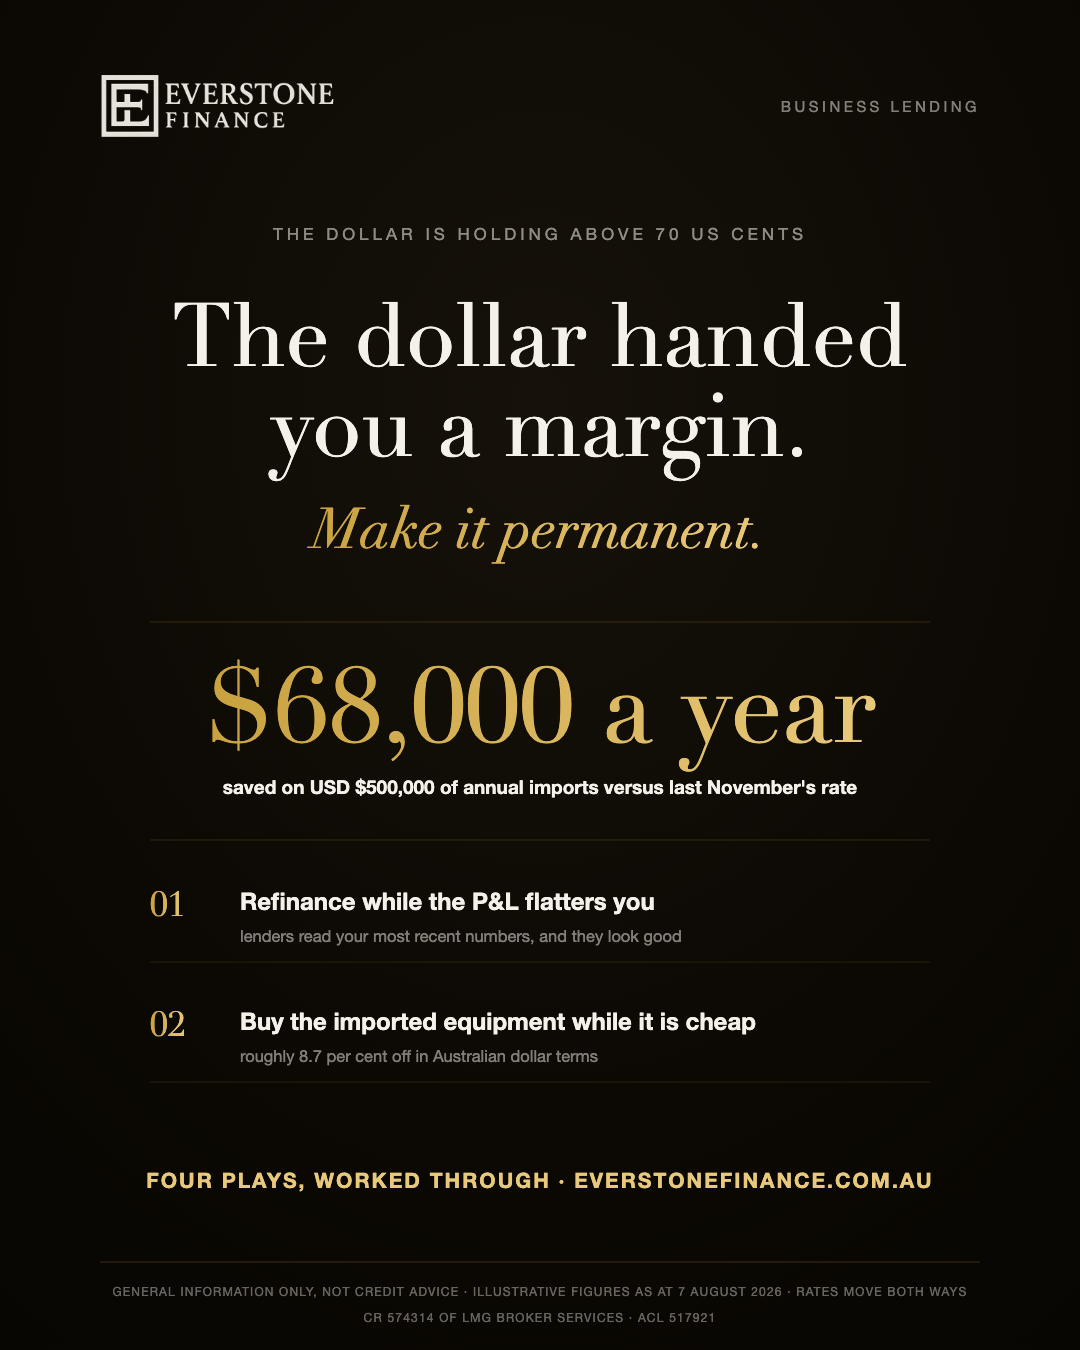
- For an importer, that is a direct cost cut: a business buying USD $500,000 of stock a year pays roughly $68,000 less in Australian dollars than at the currency’s low last November.
- Currency windfalls are cyclical. The businesses that come out ahead convert them into structural gains: a refinanced facility while the P&L looks strong, imported equipment bought while it is cheap, or the deposit on premises.
- Lenders assess your business on recent performance, so a currency-fattened profit line is worth the most at the bank while it is showing, not after it normalises.
What the dollar has done, in one paragraph
The Australian dollar climbed from about 64 US cents in late 2025 to three-year highs above 72 cents in early 2026, pulled back below 70 during the global flight to the US dollar, and is now consolidating above 70 cents, around 8 per cent stronger than a year ago. For Australian businesses that pay suppliers in US dollars, the stronger currency directly reduces the Australian dollar cost of imported stock, equipment and inputs.
The short history: the Aussie sat near 64 US cents last November, ran to three-year highs above 72 cents by early this year, gave some back when global money rushed to the US dollar, and has settled into a range above 70 cents, its strongest sustained level in months and roughly 8 per cent up on a year ago. Forecasters argue about the next move, as forecasters do. This article is not about the next move. It is about what the level you already have does to a business that imports, because that effect is sitting in your accounts right now.
What it means for an importing business
A stronger Australian dollar directly cuts the local cost of US-dollar-priced imports. Worked illustration: a business buying USD $500,000 of stock annually paid about AUD $779,000 at last November’s exchange rate near 64.15 cents, and pays about AUD $711,000 at 70.3 cents, roughly $68,000 a year less for identical stock. The saving flows straight to gross margin unless competitors force it into pricing, and it applies equally to imported equipment and machinery.
Run your own version of this arithmetic, because it is probably the fastest profit movement in your business this year. A business buying USD $500,000 of stock annually:
| At last November’s rate (~64.15c) | At today’s rate (~70.3c) | |
|---|---|---|
| Annual cost in Australian dollars | About $779,000 | About $711,000 |
| The difference | Roughly $68,000 a year, for identical stock | |
Run it on your own import bill
Same arithmetic as the table: your annual US-dollar spend divided by the exchange rate, at two rates. The defaults are the two rates used above (the November low and the level as at 7 August 2026); type today’s rate if it has moved. Illustration only, not a forecast.
Scale it to your own import bill: at these rates the saving runs at roughly 8.7 per cent of whatever you spend in US dollars. It lands quietly, spread across every shipment, which is why plenty of owners feel the P&L improving without attributing it. And the same discount applies to the biggest single import most businesses ever make: equipment and machinery. The imported ute, the CNC machine, the fit-out, the kitchen: all of it is effectively on sale in Australian dollar terms compared with last year.
Importing business feeling the stronger dollar? WhatsApp, text or call Ahmed about your facilities and whether a refinance or equipment purchase is worth a look. His own mobile, no call centre, and the first chat is free.
Four ways to make a cyclical win structural
Currency gains are cyclical and can reverse, so the durable move is converting the widened margin into permanent improvements: refinancing business debt while the profit line is strong, since lenders assess recent performance; bringing forward imported equipment purchases while the dollar is high; directing the freed cash flow toward premises, including through an SMSF; or simply building the buffer that makes the next downturn survivable. Spending the windfall as if it were permanent margin is the common mistake.
The dollar gave you this margin and the dollar can take it back. The owners who win these cycles convert the temporary into the permanent while the window is open:
- 1. Refinance the debt while the numbers flatter you. Business lending is priced and approved off your recent performance. A currency-fattened profit line makes you a stronger borrower today than you were a year ago, and our business refinance savings calculator shows what a sharper rate is worth over one, ten, twenty and thirty years. If your financials are complicated, the no-tax-returns route exists for exactly that.
- 2. Buy the imported equipment now, not later. If the machine was on the three-year plan anyway, an 8 per cent currency discount is a real number on a six-figure purchase, and asset finance spreads the cost while the discount is locked at purchase.
- 3. Point the freed cash flow at premises. $68,000 a year of margin is, roughly, the serviceability footprint of a meaningful chunk of commercial property debt. Whether directly through a commercial property loan or via your super using the structure in our step-by-step SMSF guide, the strongest version of a currency windfall is one that ends with your business paying rent to you.
- 4. Or simply build the buffer. Not glamorous, but the businesses that survive downturns are the ones holding cash when the cycle turns. A windfall parked against debt or in reserve is a windfall that keeps working after the dollar stops cooperating.
In short: spend the windfall on something that survives a weaker dollar, and put your file in front of a lender while the improvement is still in your statements.
Your P&L looks better than it did. That is exactly when the bank listens.
Bring your last year of figures and your current facilities. We will tell you plainly whether refinancing, equipment finance or a premises play stacks up on today’s numbers, and which lenders suit a business shaped like yours. Former bankers, no cost, no obligation.
Have a former banker read my improved numbers, freeWhy the timing matters at the bank
Lenders assess business borrowers on their most recent financial performance, typically the last one to two years of statements. A period of currency-improved margins strengthens serviceability now, while the improvement is visible, and that strength fades from the assessment if margins later normalise. Businesses planning to refinance, expand or buy premises within the next couple of years benefit from approaching lenders while the stronger figures are current rather than after the cycle turns.
Here is the mechanical reason not to file this under later. When a lender assesses your business, it reads your most recent financials: the last year or two of statements, the current interims. Margins improved by the currency are in those documents now. If the dollar retreats and margins normalise, next year’s statements tell a flatter story, and your borrowing position weakens with them, even though nothing about your underlying business changed.
So the sequencing writes itself: if a refinance, an equipment purchase or a premises move is anywhere in your two-year plan, the strong-dollar period is when to put your file in front of a credit team. Banking the improvement is not opportunism; it is simply refusing to let a good year go unread.
What the assessor actually reads. The last two years of statements and the current interims, in that order, and the gross margin line before almost anything else. We see it every week: a business whose margin lifted for currency reasons is assessed as a stronger business, because the assessor is reading results, not causes. That cuts both ways when the cycle turns.
Frequently asked questions
How does a stronger Australian dollar help my business?
If you pay suppliers in foreign currency, mostly US dollars, a stronger Australian dollar directly cuts the local cost of the same stock, equipment or inputs. At current levels versus last November’s low, the saving runs at roughly 8 to 9 per cent of your US-dollar spend, flowing straight into gross margin unless competition pushes it into pricing.
Should I bring forward equipment purchases while the dollar is strong?
If the purchase was planned anyway, a currency discount on an imported asset is a real saving locked in at the moment you buy, and asset finance can spread the cost without giving the discount back. Buying things you did not need is not a currency strategy; it is spending.
Does a better profit year actually change what I can borrow?
Yes. Business lending is assessed on recent performance, so a stronger year of margins improves serviceability and pricing while those figures are the current ones. The improvement stops helping once it drops out of your most recent statements, which is the argument for acting during the window rather than after it.
What if the dollar falls again?
It might; currencies cycle. That is precisely why the durable moves are structural: a refinanced rate, an asset bought at a discount, premises secured, debt reduced. Each of those survives a weaker dollar. Treating the widened margin as permanent income is the mistake to avoid.
Can I refinance my business loan if my financials are complicated?
Often, yes. Alternative documentation lending assesses a business on evidence like BAS statements and bank trading history rather than finished tax returns. Our guide to refinancing without tax returns covers who fits and what it costs.
Could the strong dollar help me buy my business premises?
Indirectly and meaningfully: the improved cash flow strengthens the serviceability that premises lending is assessed on, and the deposit can come from the business or from superannuation using an SMSF structure. With commercial property the one asset class still open to new SMSF borrowing, the two trends line up unusually well right now.
The honest summary
Nobody running a business controls the currency, and this year it has quietly handed importers their fastest margin improvement in a long time. The only question that matters is whether that improvement evaporates with the next leg of the cycle or gets converted into something that stays: a cheaper facility, a machine bought at a discount, premises, a buffer. Lenders are reading your best numbers in years right now. It costs nothing to find out what those numbers unlock.
The dollar handed you a margin. Make it permanent.
Refinance, equipment, premises or buffer: one conversation maps what your improved numbers support and which lenders want a business like yours. Former bankers, plain answers, and the honest no if the timing is wrong.
Map what my numbers unlock, freeAbout the author. Ahmed Lotfi is co-founder of Everstone Finance and a former banker who now works as a mortgage and finance broker in South Yarra, Melbourne, arranging home, investment and commercial lending for clients across Australia. Everstone Finance operates under the Best Interests Duty.