
Non-Resident Home Loans in Australia (2026): Foreign Income, Visa Holders and Foreign Buyers
Non-resident home loans are Australian mortgages written for three kinds of borrower: Australian citizens working abroad, temporary visa holders and foreign nationals. The two non-bank lenders that publish dedicated non-resident products cap lending at 75 to 80 per cent of the property value, so plan for a 20 to 25 per cent deposit plus purchase costs. Everstone Finance, a Melbourne mortgage broker, places these files by video.
Working abroad, here on a visa, or buying as a foreign national? A former banker points you to the right lenders, free.
Send your residency status, your income and its currency, and the property type. We match that to the lenders that write these loans and the deposit each expects.
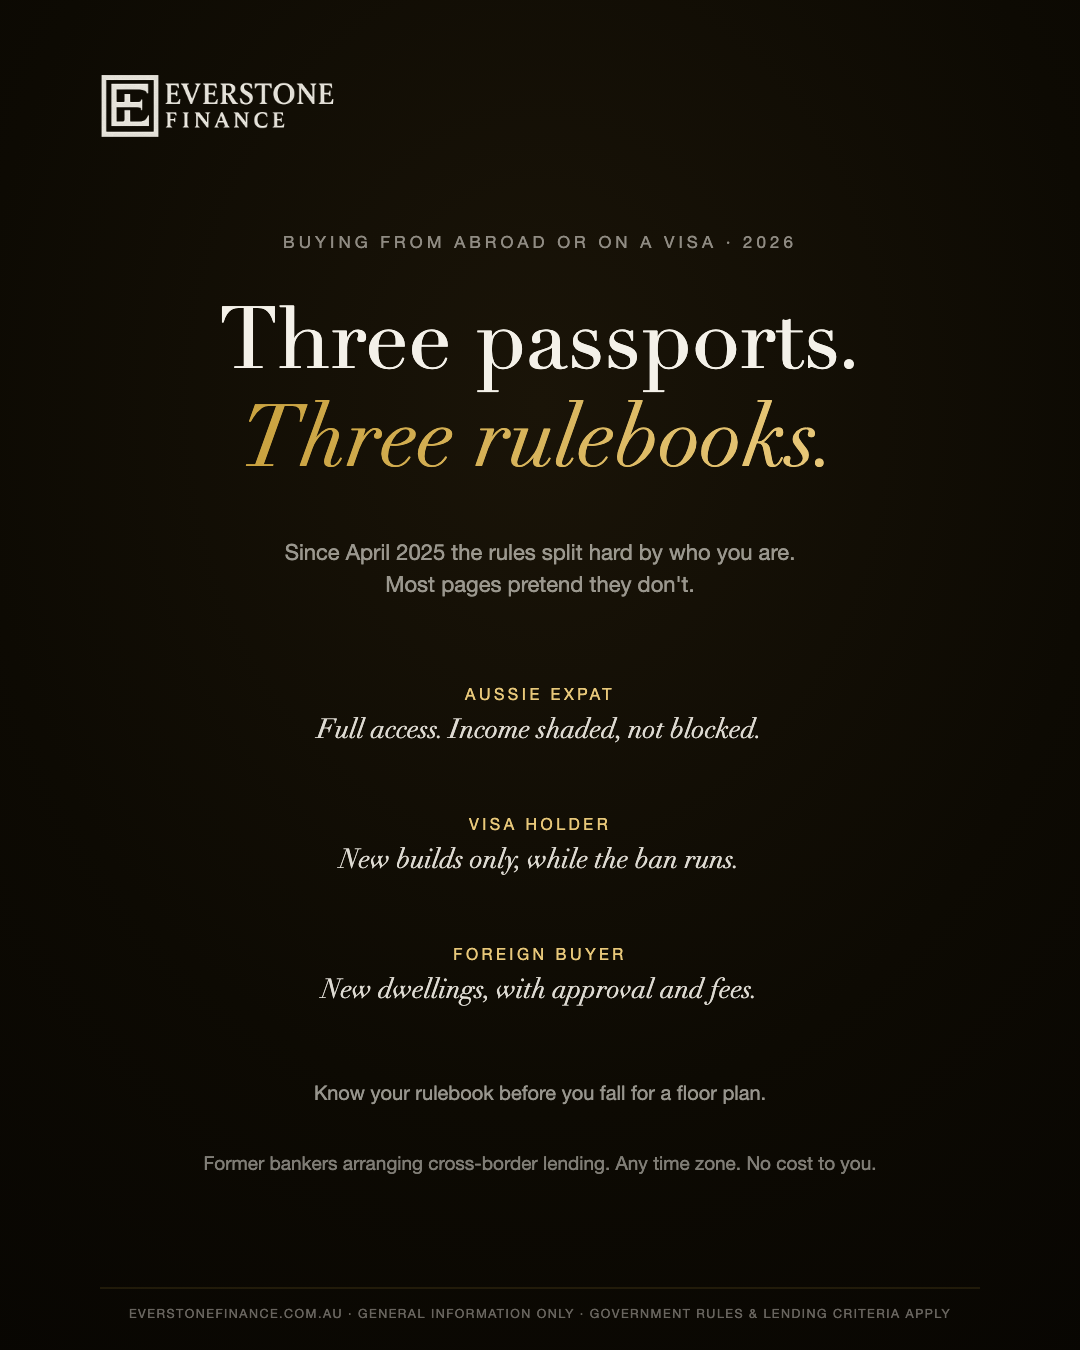
Book a non-resident lending call with a former banker- The rules split by who you are, not where your income comes from: citizen abroad, temporary resident, or foreign non-resident.
- Australian citizens overseas are exempt when buying property here: no FIRB, no ban, full access. Our expat guide covers them in depth.
- Since 1 April 2025, foreign persons including temporary residents cannot buy established dwellings, with narrow exceptions; the government has announced the ban will run to 30 June 2029. New dwellings and vacant land remain open to foreign buyers with approval and fees, plus state surcharge duties.
- Foreign income is converted to Australian dollars and shaded, typically counted at 80 per cent of gross income for widely traded currencies and 70 per cent for others.
- Book a chat with a former banker to find out which rulebook, and which lenders, apply to you.
- What a non-resident home loan is
- Which rules apply to you
- Who lends to non-residents
- Deposit
- Interest rates
- Foreign income
- Australian citizens overseas
- Temporary visa holders
- By visa subclass
- Permanent residents, New Zealand citizens and couples
- Foreign non-residents
- FIRB fees and state surcharges
- How to apply and documents
- Why Everstone Finance
- FAQ
What are non-resident home loans in Australia, and who are they for?
A non-resident home loan is an Australian mortgage written for a borrower who lives outside Australia or earns income outside Australia: an Australian citizen working abroad, a temporary visa holder, or a foreign national with no residency. The security is Australian property and the lender is Australian; the differences from a standard loan sit in three places: a lower maximum loan-to-value ratio, a haircut on foreign income, and a shorter list of lenders willing to write the file.
Those three are not the same borrower. An Australian engineer earning dirhams in Dubai, a nurse in Melbourne on a skilled visa, and an investor in Singapore who has never set foot here face three different sets of rules. Sort out which rulebook applies to you and the rest becomes navigable.
Which non-resident home loan rules apply to you: citizen abroad, visa holder or foreign buyer?
Australian citizens are exempt from foreign investment approval wherever they live, so the purchase ban does not apply to them. Temporary residents in Australia are foreign persons: since 1 April 2025 they cannot buy established dwellings, though new dwellings remain possible with approval. Foreign non-residents face the tightest rules of all.
So before anything else, find your row.
| Who you are | FIRB position | Established homes | The lending picture |
|---|---|---|---|
| Australian citizen, living anywhere | Exempt, no approval needed | Yes | Full market access; foreign income is shaded, see our expat guide |
| Permanent resident or NZ citizen | Generally treated like citizens | Yes | Broad access; income source still shapes the assessment |
| Temporary resident (work, student or partner visa) | Foreign person, rules apply | No, banned since 1 April 2025, narrow exceptions | New dwellings or vacant land with approval; lender appetite varies by visa |
| Foreign non-resident | Foreign person, approval and fees | No | New dwellings or vacant land; smaller lender pool, surcharge duties |
General information only, not legal, migration or credit advice. The foreign investment framework, its exceptions and fees are set by the Australian Government and change; check foreigninvestment.gov.au and take advice on your situation.
Which rulebook applies to you?
Pick your row and we will say what it means for the purchase and for the lending, in the words this page uses above.
Can a non-resident get a home loan in Australia, and which lenders offer non-resident lending?
Yes, from a shorter list of lenders than a standard loan. For foreign nationals, specialist lenders such as Brighten and La Trobe Financial publish non-resident products. Temporary visa holders are assessable borrowers, and appetite differs by lender. Australian citizens living overseas are usually assessed under expat policy rather than non-resident policy, a wider and cheaper lender set covered in our Australian expat home loans and expat lending guide.
The field is thin: a minority of lenders write loans for non-resident foreign nationals, deposits are expected to be substantial, and foreign income shading applies with full force.
On a visa, earning in another currency, or living outside Australia? WhatsApp Ahmed from wherever you are and talk through which rules apply to you. His own mobile, no call centre, and the first chat is free.
How much deposit do you need for a home loan for non-residents?
Plan for a 20 to 25 per cent deposit plus purchase costs. The two non-bank lenders that publish dedicated non-resident products cap lending at 75 to 80 per cent of the property value: Brighten (Evergreen and Platinum, loans from $150,000 to $15 million) at 80 per cent, and La Trobe Financial (Non-resident Loan, written for international borrowers with foreign investment approval) at 75 per cent, on loans up to $5 million.
Temporary visa holders have their own ceilings, and a sole visa holder should plan for a larger deposit. Under a major-bank-backed policy from August 2026, subclass 188, medium-term 482 and main-applicant 491 holders can be considered as sole borrowers at up to 70 per cent LVR for owner-occupied purchases, while co-borrowing with an Australian citizen or permanent resident lifts the ceiling to the standard 80 per cent. Lenders mortgage insurance is generally unavailable where any borrower is a temporary visa holder, which is why the 80 per cent ceiling is hard rather than soft.
These lender settings were checked on 11 September 2026. A harder-shaded currency or unverifiable income pushes the deposit higher. The foreign investment application fee and the state surcharges that sit on top are set out below.
Are interest rates higher on non-resident loans in Australia?
Yes, on the published non-resident products: the advertised rates sit above the rates written for Australian residents.
Advertised variable rates on those products start from 7.58 per cent p.a. (Brighten, 8.11 per cent comparison rate) and 8.39 per cent p.a. (La Trobe Financial Non-resident Loan, 8.84 per cent comparison rate), above the rates written for Australian residents, and La Trobe charges a 1.50 per cent application fee on that loan. La Trobe’s lower 7.74 per cent rate (8.18 per cent comparison rate) belongs to its separate Expatriate Loan for Australian citizens living or working abroad. Rates change without notice; these are the lenders’ published figures, read on 2 October 2026 and adjusted for the 0.25 point rise lenders passed on from 9 October 2026.
How do lenders assess foreign income for a home loan in Australia?
Cautiously and unevenly. Lenders convert foreign income to Australian dollars and then shade it, counting only a portion, with the size of the haircut varying by lender and by currency; major currencies are treated the most generously. Documentation from foreign employers and tax systems carries extra scrutiny. Lender choice moves the answer more than any other factor.
Income earned outside Australia is read through two filters. The first is conversion and shading. As a starting point, lenders typically count 80 per cent of gross income for widely traded currencies and 70 per cent for others, but the exact number depends on the lender, the currency and the year.
The second filter is evidence. Foreign payslips, employment contracts in other languages, tax statements from other systems and offshore bank accounts all get more scrutiny than their Australian equivalents, and a foreign payslip that the bank statements cannot confirm is queried, not counted.
Tax residency runs under all of it: whether you are an Australian tax resident changes how your income is assessed and taxed, and it does not always match your visa status or your address. The ATO’s guidance on tax residency is the starting point, and a cross-border accountant is the right professional to settle it. For Australians abroad, our expat guide covers the income question in more depth, currency tiers and worked example included.
Can an Australian citizen living overseas get a home loan?
Yes, and the purchase side is clear: no FIRB, no ban, full access. Australian citizens are exempt from foreign investment approval for residential land wherever they live, so the ban does not reach them, and state foreign-buyer surcharges do not apply to citizens either. The challenges are lending ones: how much of the foreign income a lender counts, and how the currency is treated.
Among the major banks, CBA and ANZ accept foreign income with shading, and each sets loan-to-value and negative gearing rules that matter for expats. NAB and Westpac do not lend to borrowers living overseas, and Macquarie requires a current Australian residential address even though it publishes an accepted currency list. For borrowers living in Australia on foreign currency income, ING and Macquarie belong on the shortlist.
Australian citizens overseas can go further with which Australian banks lend to expats in 2026 and our Australian expat mortgage broker page.
Our guide to Australian expat home loans walks through the lending challenges, worked example included. If you already hold an Australian loan, see refinancing an Australian mortgage from overseas and our guide to cash out refinancing for Australian expats.
For returning expats, the transition timing questions are covered in the expat guide, and our returning expat home loan guide covers sequencing the application before you leave.
Where do you live? Pick the guide written for your city:
Or start with the full overseas buying guide.
Reading this from another time zone? That is normal for us. Book a time with a former banker that suits your clock, and we will bring the lender map to the call.
Can temporary visa holders buy a home in Australia in 2026?
Not an established dwelling. Since 1 April 2025 the Australian Government has banned foreign persons, explicitly including temporary residents, from buying established homes, with narrow exceptions, and has announced the ban will run to 30 June 2029. The ban was originally due to end on 31 March 2027 and has been extended. A new dwelling or vacant land to build on remains possible with foreign investment approval, and permanent residency removes the restrictions entirely.
A skilled work visa, a student visa or a partner visa makes you a temporary resident, and under the Australian Government’s ban on foreign purchases of established dwellings you currently cannot buy an existing house or apartment, even to live in.
What remains open:
- New dwellings. Apartments and houses that have not been previously sold or occupied as a dwelling can still be bought by temporary residents with foreign investment approval and the associated fees.
- Vacant land to build on. Approval is generally conditional on completing construction within a set period.
- Waiting for permanent residency. PR removes the foreign person restrictions, and the deposit keeps growing in the meantime.
- Buying with an Australian spouse. Covered below.
FIRB and visa questions are legal and migration matters, so alongside the lending work, have a solicitor confirm your purchase is compliant. We arrange the finance; we do not give migration or legal advice.
Temporary resident home loans by visa subclass: can you borrow on a 482, 485, 491, 494, 444, partner or student visa?
Yes. Temporary residents are assessable borrowers; the question is which lenders, on what settings. The foreign investment framework decides what you can buy, and it treats every temporary resident the same way; each lender’s credit policy decides whether it will lend and how much, and that is where the subclass, the time left on the visa and the path to permanent residency start to matter.
The purchase rules were checked against foreigninvestment.gov.au and the ATO on 11 September 2026. The last two rows of the table cover New Zealand citizens on subclass 444, the special category visa, and permanent visa holders, who are generally treated like Australian citizens under the foreign investment rules.
| Visa | Under the foreign investment rules | What we see on the lending side |
|---|---|---|
| Subclass 482, the Skills in Demand visa (formerly Temporary Skill Shortage) | Temporary resident: new dwelling or vacant land with approval, no established homes until 30 June 2029 | The most workable temporary visa for lenders. Full-time salaried income in Australian dollars is assessed at face value; lenders differ on how long must remain on the visa and whether an employer-sponsored permanent residency pathway has to be visible |
| Subclass 485, Temporary Graduate | Temporary resident, same purchase rules | Fixed end dates make lenders cautious; a permanent full-time role, a visible skilled visa pathway and a larger deposit carry the file |
| Subclass 491 and 494, the provisional regional visas | Temporary resident, same purchase rules, and the visa conditions keep you living and working in a designated regional area | The permanent residency pathway built into the visa helps; lenders still apply their temporary resident settings until the permanent visa is granted |
| Subclass 820 and 309, partner (provisional) | Temporary resident on your own; buying together with an Australian citizen or permanent resident spouse as joint tenants is the recognised path to an established home | The most common temporary visa file we place, almost always with the citizen partner as co-borrower; Revenue NSW notes that 309 and 820 holders can be treated as ordinarily resident or as an exempt permanent resident for surcharge purposes |
| Subclass 500, student | Temporary resident, same purchase rules | Few lenders lend on student income alone; a working spouse, a parent as guarantor or a substantial deposit is usually what makes the file possible |
| Bridging visas | Foreign person until the substantive visa is granted; Revenue NSW treats bridging visa holders as foreign persons for surcharge purchaser duty unless an exception applies | Appetite is thin until the substantive visa is decided; most files wait |
| Subclass 444, New Zealand citizens on the special category visa | Exempt from foreign investment approval for residential land, so established homes are open and the ban does not apply | Assessed much like a permanent resident; if you live in New Zealand the file is an expat file on New Zealand dollar income |
| Permanent visas (189, 190, 186 and the rest) | Exempt from foreign investment approval for residential land: no fee, no ban | Full market; the only remaining question is where the income is earned and in which currency |
The loan-to-value ceilings one major-bank-backed policy sets for sole holders of some temporary visas, and for couples, are in the deposit section.
Can permanent residents, New Zealand citizens and mixed couples buy established homes?
Permanent residents and New Zealand citizens are generally treated like Australian citizens under the foreign investment rules, so the ban does not stop them buying established homes. For couples where one partner is a citizen or permanent resident and the other is not, buying together as joint tenants is the well-worn path, with legal advice to confirm the details. If you already live and work in Australia on a permanent, 444 or temporary visa, the in-Australia version of this guide is home loans for migrants and visa holders.
Permanent residents hold property rights that mirror citizens’ under the foreign investment framework, no approval and no ban, while they remain ordinarily resident in Australia; a permanent resident who has lived overseas for an extended period should confirm their position before signing. New Zealand citizens on subclass 444, the special category visa, are exempt from foreign investment approval for residential land, and on the lending side are assessed much like a permanent resident.
The mixed couple, one partner an Australian citizen or permanent resident and the other on a visa, is the most common real-world case. The established-dwelling door generally reopens here, with purchases structured as joint tenants between spouses being the recognised path under the framework’s exemptions, and a solicitor should confirm the structuring for your exact circumstances before contracts are signed.
On the lending side, lenders differ in how generously they read the second income. A major-bank-backed policy from August 2026 treats a partner co-borrowing with an Australian citizen or permanent resident as acceptable regardless of visa status, even while living overseas, and a partner co-borrowing with a New Zealand citizen as acceptable while both live and work in Australia. Under the same policy, the citizen or permanent resident partner does not need to be the higher earner. Where a permanent resident borrows with a temporary or overseas resident, FIRB approval enters the picture, which is worth confirming before contracts, not after.
Find out which rulebook, and which lenders, apply to you
Tell us your citizenship, visa and income situation and we will map what you can buy, which lenders would look at your file, and what to line up first. Straight answers across any time zone. No cost, no obligation.
Book a chat with a former bankerWhat can foreign non-residents actually buy?
New dwellings and vacant land for development, with foreign investment approval and fees, and established homes are off the table. Expect state surcharge duties on top of standard costs, a smaller pool of willing lenders, and deeper deposit requirements. It is a narrow path, but for the right purchase it remains a real one.
For a non-resident with no Australian citizenship or permanent residency, every purchase needs a foreign investment application and its fees, which scale with the property price. The purchase rules themselves, including the state surcharges and the narrow exceptions to the established home ban, are set out in our dedicated guide to the rules for foreign buyers in 2026.
What do FIRB approval and state surcharges cost foreign buyers and visa holders?
A foreign investment application fee first, then, in most states, a surcharge on top of stamp duty. Checked against foreigninvestment.gov.au and the ATO on 11 September 2026, the 2026-27 application fee is $15,600 for a property of $1 million or less and $31,300 up to $2 million, and the ATO has 30 days to decide once the fee is paid.
Fees are tiered by the value of the property and are indexed each July. The current fee schedule is published at foreigninvestment.gov.au.
Each state runs its own foreign purchaser surcharge with its own definition of a foreign person, and the definitions do not copy the federal one. Rates checked on the revenue office websites on 11 September 2026:
- New South Wales: 9 per cent surcharge purchaser duty.
- Victoria: 8 per cent foreign purchaser additional duty.
- Queensland: 8 per cent additional foreign acquirer duty.
- Western Australia: 7 per cent foreign buyers duty.
- South Australia: 7 per cent foreign ownership surcharge.
- Tasmania: 8 per cent foreign investor duty surcharge on residential property.
- Australian Capital Territory: no duty surcharge, but foreign owners are charged a land tax surcharge of 0.75 per cent of the average unimproved value each year.
Rates vary by state and change with budgets, so check the current schedule for the state you are buying in before running numbers.
New South Wales exempts permanent residents and New Zealand special category visa holders who were in Australia for at least 200 days in the preceding 12 months or who live in the property for a continuous 200 days within 12 months of the contract. Several states also add a surcharge to annual land tax, so an investor on a temporary visa should price both before exchange, with a conveyancer confirming the state test.
How do you apply for a non-resident home loan, and what documents do you need?
Confirm the lender first, then the foreign investment approval or the developer’s exemption certificate, and only then the contract: for a visa holder, that is the reverse of what most people do. A cleanly documented file is an employment letter, payslips, tax records and bank statements that reconcile, and lenders differ in what they will accept and how they verify it.
- Check lender policy. Which lenders accept your currency and on what shading, and which will lend to your visa subclass, is checked against current policy before an application goes anywhere. Off-the-plan contracts signed before the lending is checked are where visa holder files go wrong.
- Assemble the documents. The employment letter, the payslips, the tax records and the bank statements are read as one story, and a cleanly documented file moves a cross-border application from difficult to routine.
- Have approval in hand. For a foreign person, approval or an exemption certificate has to be in hand before you sign an unconditional contract; a developer’s exemption certificate can cover a new apartment so that you do not apply yourself.
- Assemble the professional team. A solicitor to confirm the purchase is compliant and a cross-border accountant to settle tax residency, before falling in love with a floor plan.
Prefer to talk? Book a time; the calendar shows slots in your time zone.
Why do cross-border borrowers work with Everstone Finance?
Because cross-border lending is two problems at once, a legal rulebook and a lender map, and the lender map is unpublished. Everstone Finance works with expats, visa holders and foreign buyers, knows which lenders accept which incomes and visas under current policy, works across time zones, and coordinates with your solicitor and accountant rather than around them.
Everstone Finance is a Melbourne mortgage broker across 40+ lenders. Cross-border files reward the kind of preparation that suits former bankers: which lenders accept your currency and on what shading, which will lend to your visa subclass, and how a mixed couple’s two incomes stack at each institution. We run these files over video and email, the same way we handle our expat clients from Singapore to San Francisco, arranging the lending while your solicitor handles the foreign investment compliance and your accountant handles the tax residency question.
The lender pays our commission on settlement, you pay nothing for the service, and the Best Interests Duty binds every recommendation we make to your interests. Moneysmart’s guide to using a mortgage broker explains the arrangement.
Non-resident home loans: frequently asked questions
What is a non-resident home loan?
A non-resident home loan is an Australian mortgage for a borrower who lives outside Australia or earns income outside Australia, secured over Australian property. Compared with a standard loan it carries a lower maximum loan-to-value ratio, a haircut on foreign income and a shorter list of willing lenders. Australian citizens working abroad, temporary visa holders and foreign nationals all fall under it, but on different terms.
Can a non-resident get a home loan in Australia?
Yes, from a shorter list of lenders than a standard loan. For foreign nationals, specialist lenders such as Brighten and La Trobe Financial publish non-resident products, and deposits are expected to be substantial. Temporary residents are assessable borrowers; the question is which lenders, on what settings.
How much deposit does a non-resident need for an Australian home loan?
Plan for at least 20 per cent plus purchase costs. The published non-resident products cap lending at 80 per cent of the property value at Brighten and 75 per cent at La Trobe Financial, and a major-bank-backed policy from August 2026 sets sole holders of certain temporary visas at up to 70 per cent for owner-occupied purchases. A harder-shaded currency or unverifiable income pushes the deposit higher.
Can a temporary resident get a home loan in Australia?
Yes. Temporary residents are assessable borrowers; the question is which lenders, on what settings. Appetite depends on the visa subclass, the time left on it, your occupation and income, the size of the deposit and whether a permanent residency pathway is visible. The purchase itself is limited by the foreign investment framework to new dwellings and vacant land until 30 June 2029, with approval.
Can a New Zealand citizen on subclass 444, the special category visa, get a home loan in Australia?
Yes. New Zealand citizens on subclass 444, the special category visa, are exempt from foreign investment approval for residential land, so established homes are open and the ban does not apply. On the lending side they are assessed much like a permanent resident, and if you live in New Zealand the file is an expat file on New Zealand dollar income.
Can a foreign buyer living overseas get a home loan and buy property in Australia?
Yes, within a narrow lane. New dwellings and vacant land for development remain open to foreign buyers with foreign investment approval and fees, while established homes are off the table during the ban. Buyers should also budget for state surcharge duties on top of ordinary costs and expect a smaller pool of lenders with deeper deposit expectations.
Which lenders accept foreign income for a mortgage in Australia?
Among the major banks, CBA and ANZ accept foreign income with shading. NAB and Westpac do not lend to borrowers living overseas, and Macquarie requires a current Australian residential address even though it publishes an accepted currency list. For borrowers living in Australia on foreign currency income, ING and Macquarie belong on the shortlist. For foreign nationals, specialist lenders such as Brighten and La Trobe Financial publish non-resident products. Our bank-by-bank expat comparison sets out the sources.
Can an Australian citizen living overseas get a home loan in Australia?
Yes. Australian citizens are exempt from foreign investment approval for residential land wherever they live, so the ban does not reach them. The challenges for an expat are lending ones instead: how much of the foreign income a lender counts, and how the currency is treated. Citizens living overseas are usually assessed under expat policy rather than non-resident policy, a wider and cheaper lender set.
Sources
Related guides
About the author. Ahmed Lotfi is co-founder of Everstone Finance and a former banker who now works as a mortgage and finance broker in South Yarra, Melbourne, arranging home, investment and commercial lending for clients across Australia. Everstone Finance operates under the Best Interests Duty.
The rulebook is complicated. Your next step is not.
One conversation sorts your situation into the right rulebook, the right lenders and a realistic timeline, whether you are in Melbourne on a visa or watching Australian property prices from abroad.
Book a chat with a former banker